UK savings: two bank brands can share one £120,000 protection limit
FSCS deposit protection follows the authorised firm, not the number of accounts. Shared licences and joint-account shares can change what the headline limit covers.
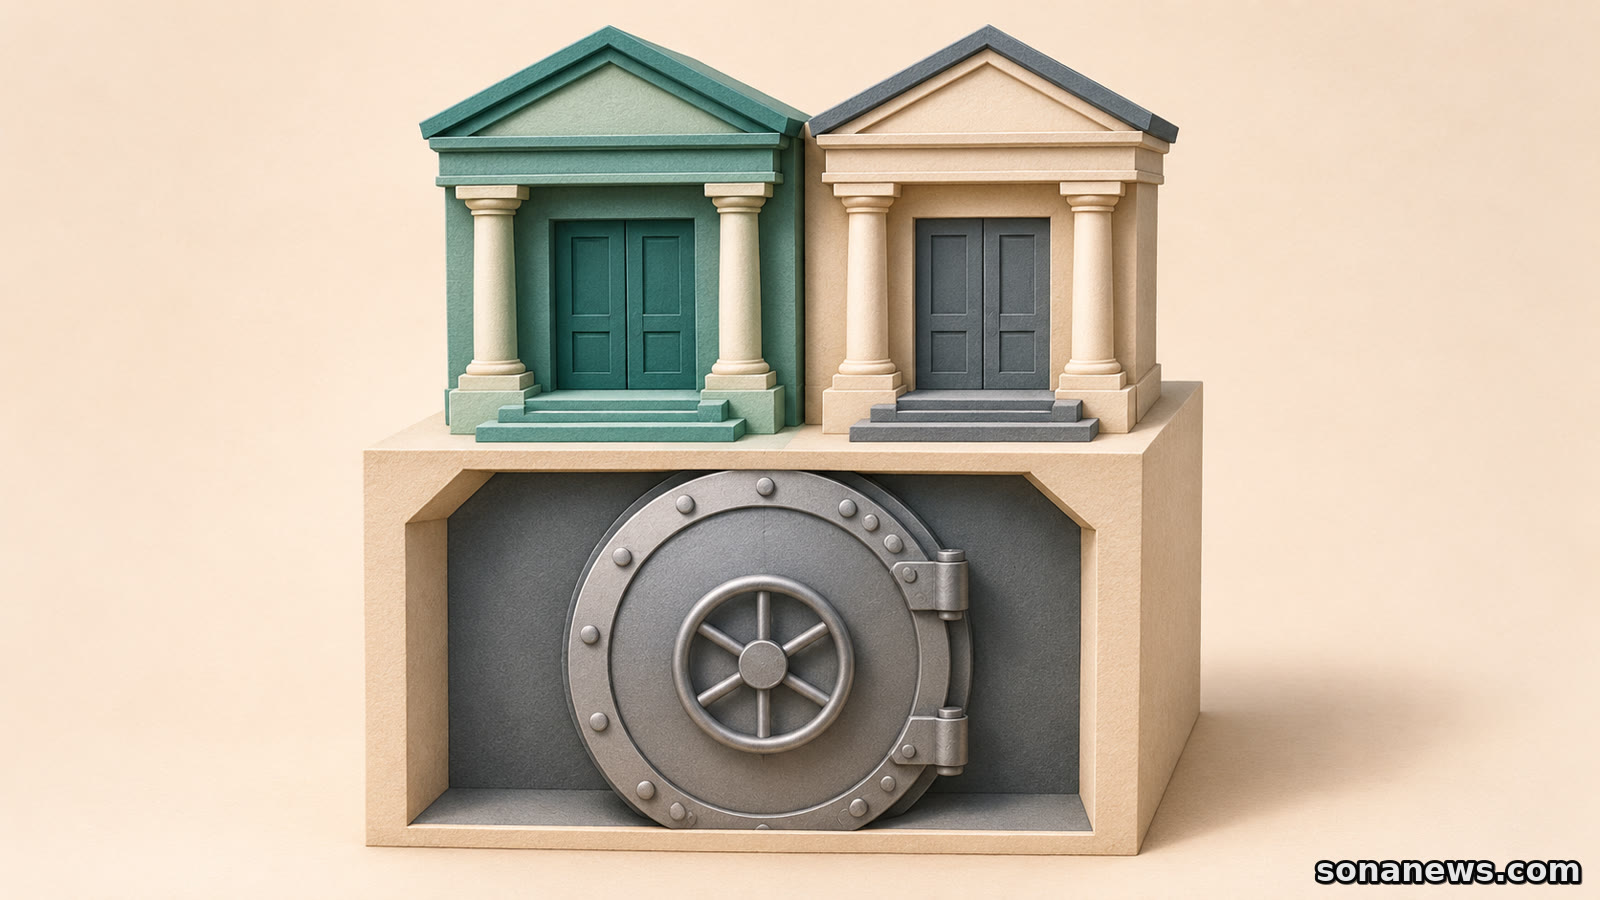
Two savings accounts with different bank names can look like two separate safety nets. Under the UK's Financial Services Compensation Scheme, they may be using the same one. If the brands share a banking licence, the ordinary deposit-protection limit applies to a person's combined eligible deposits, not separately to each brand.
The current limit is £120,000 per eligible person, per authorised firm. It took effect on 1 December 2025, replacing £85,000. This is an explanation of the rules already in force, not a new November 2026 increase or a warning that a particular bank is in difficulty.
For someone comparing accounts, the distinction is between the name on the product and the institution behind it. Another account number, different branding or a separate login does not by itself create another compensation allowance. The question is which authorised deposit taker holds the money, and what else the same person holds there.
The limit follows the licence
The FSCS explains that a banking firm can operate under more than one brand. Those brands can appear unrelated to customers while sharing the same banking licence. In that case, the scheme treats the relevant accounts together when applying its deposit limit.
A hypothetical example makes the boundary clear. Suppose one eligible person holds £80,000 with one brand and £60,000 with another that shares its licence. The combined balance is £140,000. Under the ordinary £120,000 limit, £20,000 would sit above that limit, assuming no special protection applies. It is not two independently protected balances simply because each account is below £120,000.
This is an illustration of the compensation ceiling, not a prediction that the excess will be lost. FSCS protection concerns an authorised provider failing and being unable to return deposits. An amount outside its ordinary ceiling is not evidence that the provider is about to fail.
The reverse shortcut is unreliable too: a familiar group name alone is not the full test. The operative boundary is the authorised firm and shared licence. The FSCS's guidance points readers to the Financial Services Register to identify other names under which their bank operates. Branding is a starting point for the check, not its conclusion.
A joint account is not a separate allowance for each account
Joint accounts are eligible for deposit protection, but the rule remains per eligible person. The FSCS's protection checker assumes two account holders with equal shares. With those assumptions, a joint account can have up to £240,000 protected if neither person has other deposits using the same allowance.
That qualification matters. A person's share of a joint account and their individual account at the same authorised firm are considered together. Opening a joint account does not leave that person's sole-name deposits outside the calculation, and several joint accounts do not create an unlimited sequence of fresh allowances.
The checker lets users distinguish an individual or sole-trader account from a joint account and from accounts for charities or limited companies. Those categories should not be treated as interchangeable. Ownership and legal structure can change how protection is assessed; the simple two-person example does not settle a business account or an unusual ownership arrangement.
The checker is useful, but not a guarantee
The FSCS's bank and savings protection checker can bring multiple accounts into one view. It uses information from the FCA's Financial Services Register and groups associated names under a Firm Reference Number, or FRN. That can expose a connection that separate product names obscure.
Its own disclaimer is important. The tool provides information, does not guarantee accuracy, and tells users to confirm details with the individual bank, building society or credit union and consult the Register. A search result is not a personal compensation decision. This article has not run checks on an individual customer's accounts or certified any named provider.
A practical information check therefore has three parts: the account's deposit-taking institution, any other accounts sharing that authorisation, and the ownership of the money in each account. The relevant comparison is between those facts and the protection rules, rather than between the number of brands on a list.
Large temporary balances have a separate test
The ordinary limit is not the only protection available. The FSCS says certain qualifying temporary high balances can be protected up to £1.4 million for up to six months. Examples of qualifying life events include a home sale or an inheritance.
That is not a general £1.4 million allowance for every savings account, nor does a large balance automatically qualify. The source of the money and the temporary-high-balance conditions matter. A saver cannot infer eligibility merely from seeing an unusually large amount on a statement.
The Prudential Regulation Authority confirmed the higher ordinary and temporary-high-balance limits in November 2025. Its announcement distinguishes the final £120,000 ordinary limit from an earlier £110,000 proposal. Old articles, recordings and consultation documents can therefore contain figures that are not the current ordinary limit.
A deposit rule, not a promise about every financial product
The £120,000 figure is the deposit-protection limit. It is not a blanket promise about investments, pensions or every product marketed as a place to keep money. The FSCS also says it cannot protect e-money or payment-services firms under this deposit protection; money held with a bank through a savings platform requires attention to the underlying deposit arrangement.
The useful takeaway is narrower than “use more banks”. Two names may still lead back to one authorised firm, while a joint-account balance has to be understood through its owners' shares. Establishing that structure explains what the limit means. It does not, by itself, decide which account is suitable or what any individual should do with their savings.
Editorial note. This article provides general information about UK deposit protection, not personal financial or legal advice. It does not recommend an account, provider or transfer, assess a bank's financial condition, or determine anyone's eligibility for compensation. Protection depends on the product, authorised institution, ownership and applicable scheme rules; individual circumstances require confirmation with the relevant provider or scheme.
Sources
- FSCS, “Deposit protection limit”, reopened 16 November 2026. Confirms the current £120,000 limit, 1 December 2025 start date, aggregation across brands sharing a licence, deposit-only scope and qualifying temporary-high-balance limits
- FSCS, “How do banking licences affect FSCS protection?”, reopened 16 November 2026. Supports multiple trading brands under one licence and the Register check. Named-bank examples and historical podcast figures are not copied into the article
- FSCS, “Bank & savings protection checker”, reopened 16 November 2026. Supports FRN grouping, the tool's accuracy disclaimer, joint-account assumptions and aggregation, account-type distinctions, exclusions and platform caveats. No personal account details were entered or individual result obtained
- Bank of England/PRA, “PRA confirms FSCS deposit limit to be increased to £120,000 from 1 December”, published 18 November 2025, reopened 16 November 2026. Confirms final rules versus the earlier £110,000 proposal, effective date, per-depositor/institution basis and temporary-high-balance change. Historical announcement, not new 2026 news
Help us improve
Was this article useful?
One anonymous tap helps Sona improve future reporting, headlines and source context.
Up next
Unlike buy now, pay later, traditional layaway leaves the goods with the seller until payment is complete. Refund terms and the point at which stock is set aside deserve separate checks.
Continue readingMore in Money